
 0800 043 0725
Is Equity Release Right For You ?
Whether Equity Release is right for you, will be based on your own personal circumstances and a range of different factors unique to you. Equity release could be a good idea if you’re Looking to do one of the following things ;
- Pay off an existing mortgage or any other forms of debt such as a loan, or credit card
- Supplement your retirement income
- Gift family members to perhaps help them get on the property Ladder or help them through university
- Do home or garden improvements
With over 300 different equity release plans now available, there has never been a better time to find the right plan for you.
There are now more features and flexible options to choose from and with the right advice you can find a tailored plan to fit your unique circumstances. Options include
1) Lump Sum or smaller withdrawals as and when you need the money
If eligible, you have the flexibility to release different amounts of cash, as and when you require the money, rather than having to take one single lump sum right at the start and be charged interest on what you do not use.
This may suit people who would prefer smaller installments over time instead of needing to pay off or pay for a one off Payment.
2) Making Voluntary Payments
With certain plans you have the flexibility to pay the interest off each year, so there is no additional interest to be repaid on the original loan, when you pass away or go into long term care. By making these voluntary payments during the entire life of the plan, it means there is no rolled up interest or compound interest.
This may suit people who want to avoid the rolled up interest and keep as much of the value in their estate as possible – thereby maximising the inheritance they can leave their family and beneficiaries.
3) Inheritance Protection
With certain plans, you can guarantee an inheritance for your loved ones by ring-fencing a proportion of your property value with a protected Lifetime Mortgage.
This may suit people who want to guarantee that a percentage of the future value of their home will be left to their family when the property is sold, regardless of how much interest accrues.
4) Downsizing Protection
This option allows you to downsize and repay your equity-release plan in full – either voluntarily or if the new property does not meet your lender’s criteria – without incurring any early repayment charges
This may suit people who want to have the peace of mind And flexibility that they can move house in the future And know they will not be penalized with a hefty charge if their new property doesn’t meet the existing lender’s criteria.
The best way to find out if Equity Release is right for you is to talk to an independent Equity Release adviser. As part of a Free, no obligation consultation, the adviser will review your individual circumstances and assess if Equity Release is suitable for you. If it is not, the adviser will tell you and you can then rule it out
When determining if Equity Release is right for you, below are some facts around Lifetime Mortgages to help you;
- There are no monthly repayments unless you choose a lifetime mortgage plan that lets you repay some of the interest
- You can live in your home for the rest of your life
- You continue to have full ownership of your home
- You benefit from any increase in the value of your property
- You will never owe more than the value of the property
- You have the flexibility to use the money as and when you like with a ‘drawdown’ facility (with this type of plan
- you only pay interest on the money you have taken, not the amount held in reserve)
- You have the flexibility to move in the future

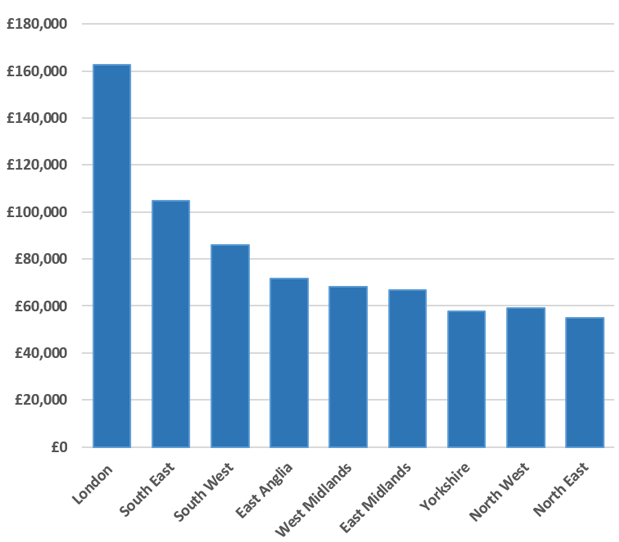
Average Amount of Equity Released By Region, Q4 2020*
Product Mix Q4, 2020

Popular uses of equity release Q4, 2020*
-

61%
Improve their Home and/or garden
-

28%
Paying off debt (credit cards / loans)
-
23%
Go on holiday
-

27%
Gift money to family / friends
-

20%
Clear outstanding mortgage
Is Equity Release Right For You ?
Whether Equity Release is right for you, will be based on your own personal circumstances and a range of different factors unique to you. Equity release could be a good idea if you’re Looking to do one of the following things ;
- Pay off an existing mortgage or any other forms of debt such as a loan, or credit card
- Supplement your retirement income
- Gift family members to perhaps help them get on the property Ladder or help them through university
- Do home or garden improvements
With over 300 different equity release plans now available, there has never been a better time to find the right plan for you.
There are now more features and flexible options to choose from and with the right advice you can find a tailored plan to fit your unique circumstances. Options include
Average Amount of Equity Released By Region, Q4 2020*
1) Lump Sum or smaller withdrawals as and when you need the money
If eligible, you have the flexibility to release different amounts of cash, as and when you require the money, rather than having to take one single lump sum right at the start and be charged interest on what you do not use.
This may suit people who would prefer smaller installments over time instead of needing to pay off or pay for a one off Payment.
Click Here To Check Eligibility2) Making Voluntary Payments
With certain plans you have the flexibility to pay the interest off each year, so there is no additional interest to be repaid on the original loan, when you pass away or go into long term care. By making these voluntary payments during the entire life of the plan, it means there is no rolled up interest or compound interest.
This may suit people who want to avoid the rolled up interest and keep as much of the value in their estate as possible – thereby maximising the inheritance they can leave their family and beneficiaries.
3) Inheritance Protection
With certain plans, you can guarantee an inheritance for your loved ones by ring-fencing a proportion of your property value with a protected Lifetime Mortgage.
This may suit people who want to guarantee that a percentage of the future value of their home will be left to their family when the property is sold, regardless of how much interest accrues.
Popular uses of equity release Q4, 2020*
-
61%
Improve their Home and/or garden
-
28%
Paying off debt (credit cards / loans)
-
23%
Go on holiday
-
27%
Gift money to family / friends
-
20%
Clear outstanding mortgage
Product Mix Q4, 2020
4) Downsizing Protection
This option allows you to downsize and repay your equity-release plan in full – either voluntarily or if the new property does not meet your lender’s criteria – without incurring any early repayment charges
This may suit people who want to have the peace of mind And flexibility that they can move house in the future And know they will not be penalized with a hefty charge if their new property doesn’t meet the existing lender’s criteria.
The best way to find out if Equity Release is right for you is to talk to an independent Equity Release adviser. As part of a Free, no obligation consultation, the adviser will review your individual circumstances and assess if Equity Release is suitable for you. If it is not, the adviser will tell you and you can then rule it out
When determining if Equity Release is right for you, below are some facts around Lifetime Mortgages to help you;
- There are no monthly repayments unless you choose a lifetime mortgage plan that lets you repay some of the interest
- You can live in your home for the rest of your life
- You continue to have full ownership of your home
- You benefit from any increase in the value of your property
- You will never owe more than the value of the property
- You have the flexibility to use the money as and when you like with a ‘drawdown’ facility (with this type of plan
- you only pay interest on the money you have taken, not the amount held in reserve)
- You have the flexibility to move in the future